Should You Waive Contingencies to Win an Offer in Orange County?
Should You Waive Contingencies to Win an Offer in Orange County?
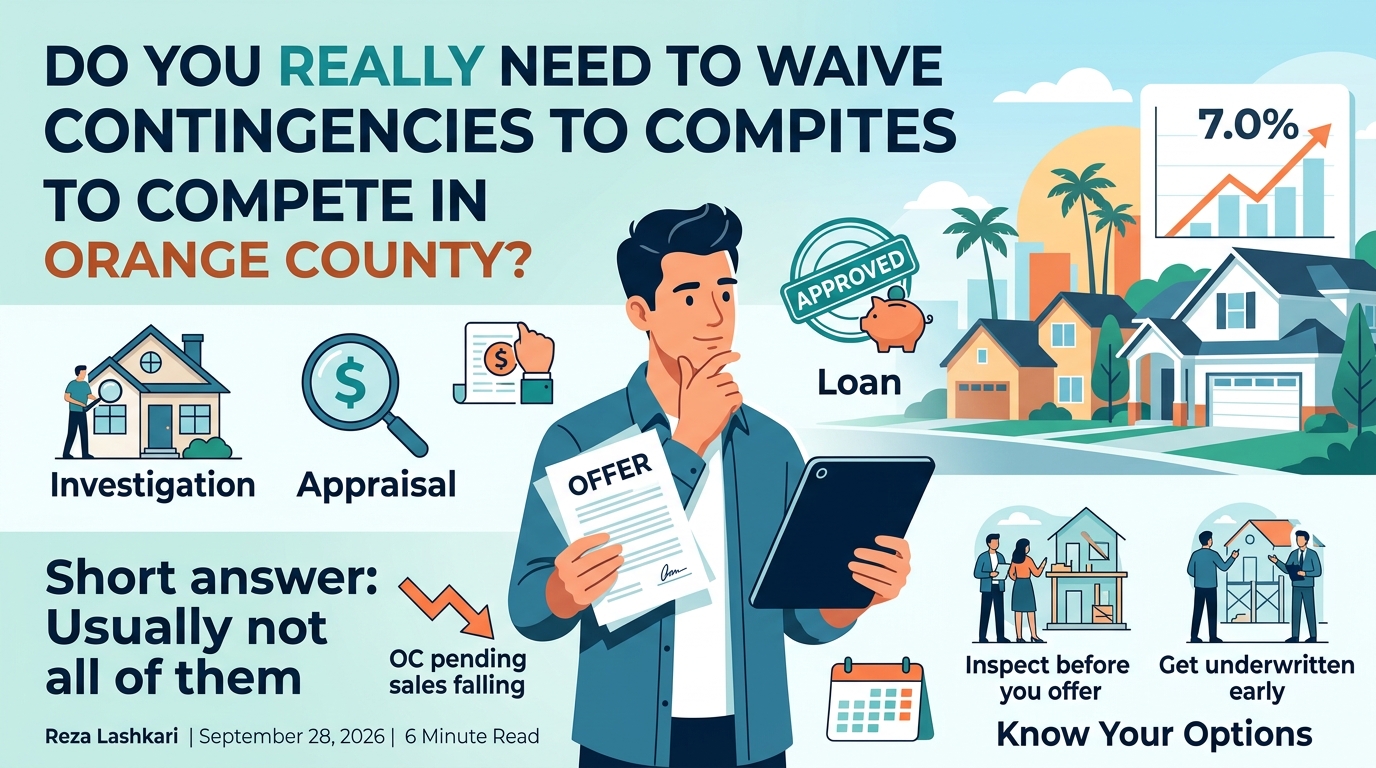
Reza Lashkari | September 28, 2026 | 6 Minute Read
Short answer: Usually not all of them. With Orange County pending sales falling and homes taking longer to sell, most buyers don't need to waive their protections to compete. Shortening your contingency periods, inspecting before you offer, and getting your loan underwritten early can make an offer just as attractive without putting your deposit at risk. If you do waive something, know exactly how much cash you could lose and how you'd cover an appraisal gap.
What Has Changed in the Market?
Rates matter here because they change how sellers and buyers behave. Freddie Mac reported the average 30-year fixed rate at 7.03% on September 24, up from 6.30% a year ago. According to a September 21 weekly report from OC Real Estate Inc., Orange County pending sales dropped to 1,793, the first reading below 1,800 since February, and the median home is taking 46 days to sell. Homes under $1 million are cooling first, and the $1 million to $2 million range is taking a median of 40 days.
That is not a market where every buyer has to waive everything to win. A South Orange County market review written earlier this year noted that buyers can now ask for help with closing costs, a repair credit, or a rate buydown rather than waiving contingencies. Well-priced homes still draw competition, though, so it helps to know your options.
What Are the Main Contingencies in a California Contract?
On the standard C.A.R. purchase agreement, buyers typically have three main contingencies:
- Investigation (inspection) contingency: lets you inspect the home and review disclosures, the title report, and association documents. The default period is 17 days. In our market, removals often happen in 10 to 15 days.
- Appraisal contingency: protects you if the home appraises below the price. The default is also 17 days.
- Loan contingency: protects you if your financing falls through. The default is 17 days.
One thing catches buyers off guard: a contingency does not expire when its date passes. You remove it in writing on a Contingency Removal form, or it stays alive. If it stays alive past the deadline, the seller can issue a Notice to Buyer to Perform, which gives you at least two days to remove it or cancel.
What Is at Risk if You Waive?
Once your contingencies are removed, canceling without a contractual reason can put your deposit at risk. For owner-occupied homes with four or fewer units, a liquidated damages provision is presumed valid up to 3% of the purchase price. On a $1,500,000 home, that is $45,000.
Waiving specific protections shifts specific risks to you:
- Waiving inspection: you accept the home's condition, including problems you can't see. A single unexpected roof, plumbing, or foundation issue can cost far more than the edge you gained.
- Waiving appraisal: you agree to cover any gap between the price and the appraised value in cash.
- Waiving loan: you're committing to close even if your financing falls through.
What Does an Appraisal Gap Really Cost?
Here's an illustration. You offer $1,500,000 with 20% down, planning to put down $300,000 and borrow $1,200,000. The home appraises at $1,450,000, so the gap is $50,000.
The lender bases the loan on the lower value, so it will lend 80% of $1,450,000, or $1,160,000. To close at $1,500,000, you would need $340,000 in cash, about $40,000 more than you planned. If you waived the appraisal contingency, you have no contractual right to renegotiate or walk away. You either come up with that cash or risk your deposit.
HomeLight reports that about 8% of appraisals came in below the sale price in 2024, and that roughly 19% of buyers waived their appraisal contingency in October 2025 to strengthen their offers. Low appraisals happen more often in fast-rising markets, but they happen in every market.
How Can You Strengthen an Offer Without Waiving Everything?
Sellers evaluate more than price. They look at contingency length, deposit size, and how believable your financing is. There are ways to send those signals without giving up your protections:
- Shorten the periods. Local agents recommend inspection windows of about 10 to 14 days and loan and appraisal windows of about 17 to 21 days, rather than open-ended timelines.
- Inspect before you offer. If you can review the property, disclosures, and association documents before writing the offer, you may be able to shorten or remove the inspection contingency with more confidence.
- Get underwritten early. A fully underwritten pre-approval carries more weight than a basic pre-qualification, especially in higher price ranges.
- Offer a strong deposit. Deposit at 3% reads differently than one at 1%, though you should be comfortable with the amount at risk.
- Cap an appraisal gap. Instead of waiving, you can commit to covering a defined gap, such as a set dollar amount, if you can afford it.
- Be flexible on timing. Sellers often value close dates and rent-backs more than buyers expect.
Avoid open-ended contingency periods, and avoid asking for concessions on a home that is already priced for its condition.
When Does Waiving Something Make Sense?
Waiving can be reasonable when:
- You've already inspected and are comfortable with the condition
- You have real cash reserves to cover an appraisal gap or a failed sale
- The competition is real, and your agent has a read on how the other offers are structured
- You understand the deposit at risk and could absorb losing it
It doesn't make sense when the waiver is the only thing standing between your offer and a stretch you can't afford, or when the property has unanswered questions.
What If You Have a Home to Sell?
A sale contingency is a different animal. It can make an offer weaker because the seller has to wait for your home to sell. If that's your situation, look at your options for buying before you sell. I compare them in our post on whether to sell first or buy first when rates are over 7%.
Frequently Asked Questions
Should I waive the inspection contingency in California?
Only with care. Waiving it means you accept the home as is, including hidden problems. A safer alternative is to inspect before you offer, or to shorten the inspection window to about 10 to 14 days.
What happens if I waive the appraisal contingency and the home appraises low?
You'd need to cover the gap in cash, since the lender bases your loan on the lower appraised value. If you can't or won't, you risk losing your deposit.
How much deposit can I lose if I back out after removing contingencies?
For owner-occupied homes with four or fewer units, a liquidated damages clause is presumed valid up to 3% of the purchase price. That's $45,000 on a $1.5 million purchase. Your contract terms control, so review them with your agent.
Do contingencies expire on their own?
No. You have to remove them in writing, or they stay active until you do. The seller can issue a Notice to Buyer to Perform, which gives you at least two days to remove them or cancel.
Can I compete without waiving contingencies in Orange County?
Often yes. A short, well-defined contingency schedule, strong financing, a solid deposit, and flexibility on timing can make an offer competitive without giving up all protection.
Ready to Write a Stronger Offer?
Competing against cash offers without a home to sell? Our Dream Program gives you the strength of a cash buyer so your offer stands out. Learn more about the Dream Program, or use the contact form on this page and I'll help you build an offer that's competitive without taking on risk you can't afford.
 About Reza Lashkari
Reza Lashkari is the Team Leader of L&L Homes Team at Real Broker, with 13+ years of experience helping buyers and sellers across Orange County. A Mission Viejo resident and longtime local youth sports coach, Reza guides families through every step of buying, selling, and relocating, whether they are moving up, downsizing, or moving across the country.CA DRE #02195314 | Broker DRE #02022092 | 949-826-8100 | reza@llhomesteam.com
This article is for general information only and is not legal, tax, or financial advice. Rates, fees, and eligibility for loans and programs change frequently and vary by lender. The figures above are published estimates and illustrations, not quotes. Consult your lender and tax professional about your situation. Reza Lashkari, CA DRE #02195314, L&L Homes Team at Real Broker (Broker DRE #02022092). Equal Housing Opportunity.
Tags: Buying, Orange County, Contingencies, Rising Interest Rates
Categories
Recent Posts
Realtor License ID: 02195314, 9527841, RES.0044054
+1(949) 826-8100 | reza@llhomesteam.com